
Why Wait Until They’re 65?
Written by Nancy Knous
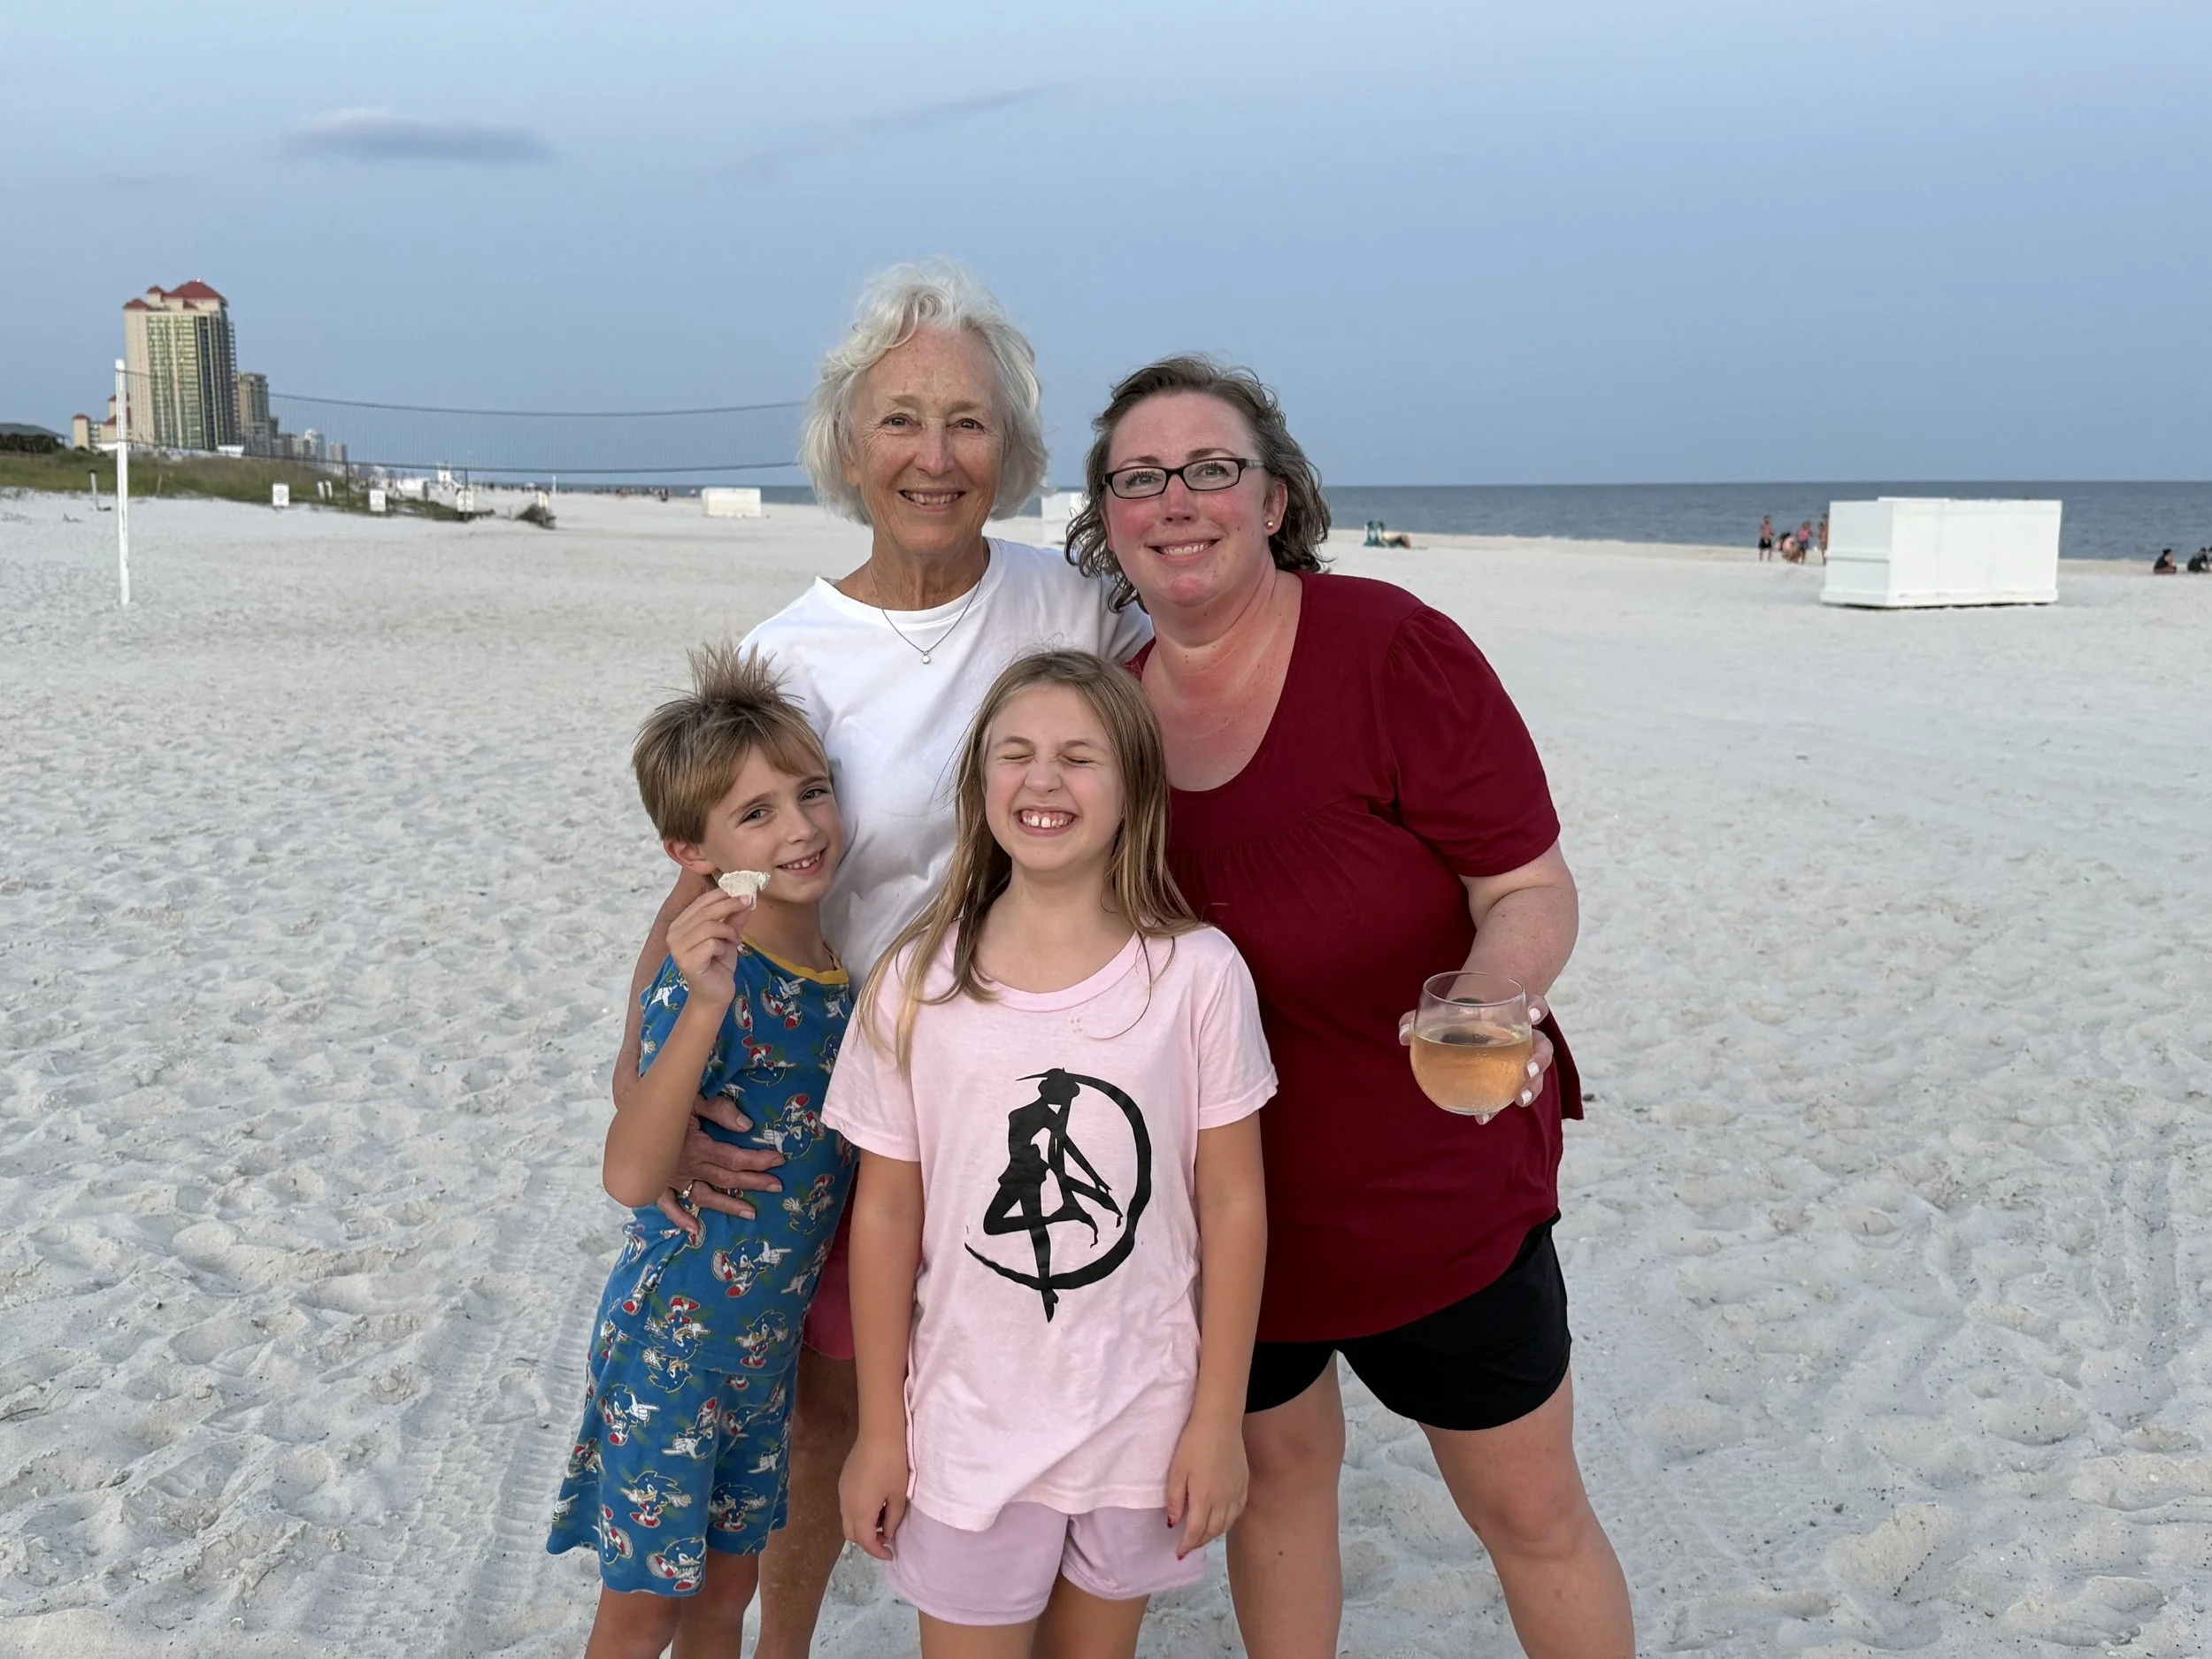
Several years ago, I read a book about retirement and estate planning that made a point I have never forgotten:
Most people inherit money when they’re 65. Most people need money when they’re 35.
I’ve thought about that a lot.
In fact, it has changed the way I give money to my family. I’ve tried to remember what my own financial life looked like when I was 35 and what would have made a meaningful difference to me then. And when I look at the younger members of my family who are around that age, many of them raising small children, I realize how much more useful some of that money can be now rather than decades from now.
There are several ways I’ve chosen to help, and a few I would recommend considering if you are in a position to do the same.
529 Plans
Sometimes I think of a 529 as the grandparents’ education fund, although you certainly don’t have to be a grandparent to establish or contribute to one. They can be wonderful tools for helping grandchildren, nieces, nephews or other family members with education expenses.
There are a number of tax and planning benefits associated with 529 plans, and your financial advisor or tax professional can explain the details. One of my favorite benefits is simple: the money has the opportunity to grow tax-free, and withdrawals for qualified education expenses are generally tax-free as well.*
For someone who wants to help younger generations without simply handing them cash, I think education is a beautiful place to start.
The $19,000 Gift
Under current federal law for 2026, an individual can generally give up to $19,000 annually to another individual without using any of his or her lifetime gift and estate tax exemption. A married couple may potentially give $38,000 to the same person.
Again, I think about myself in my 30s.
What could I have done with an unexpected $19,000?
I could have paid down debt or student loans. I could have added to my savings and created a little more financial security. I could have put it toward home repairs. I might even have treated myself to something I really wanted—and then put the rest into savings.
In short, $19,000 would have made a difference.
And an annual gift like that could make an even greater difference.
There is some prudence required here. I don’t want a gift to become an expectation or something someone begins counting on in next year’s budget. Whenever I have made gifts like this, I have tried to be clear that it is a one-time gift.
It may turn out not to be a one-time gift. But I want it understood that way when I give it.
You Can Give More
The $19,000 annual exclusion is not a limit on how much you are legally allowed to give.
You can give considerably more.
Generally, the amount above the annual exclusion is applied against your lifetime gift and estate tax exemption. For 2026, the federal basic exclusion amount is $15 million per individual. Larger gifts may require filing a federal gift tax return, even when no gift tax is actually due.
I recently had a client give $100,000 to a family member to help with the purchase of a home. Obviously, that was considerably more than $19,000. But it was something the client could afford, wanted to do, and believed would make a significant difference in that family member’s life.
The paperwork can be handled. Your CPA, attorney, and financial advisor can help you determine the tax and estate-planning implications before making a substantial gift.
Giving Requires Discernment
Of course, all of this assumes something important: that giving the money is actually good for the person receiving it.
Money can help. It can also enable poor decisions, create dependency or complicate relationships. Being able to afford a gift doesn’t automatically mean giving it is wise.
So generosity requires discernment, too.
Why I’m Giving More While I’m Alive
I had my first will prepared when I was 28, and I have probably updated it five times since then.
That is one of the great things about a will: it can—and should—change as your life, your assets, and your thinking change.
My own thinking certainly has.
Increasingly, I find myself wanting to give more to family during my lifetime rather than simply leaving it to them someday. And I have discovered something I hadn’t fully appreciated before:
There is tremendous joy in getting to see what the gift does.
I can see a young family become a little more financially secure. I can help educate a child. I can help someone buy a home, eliminate a burden or take advantage of an opportunity that might otherwise have been out of reach.
There may still be money to leave someday. There may still be charitable organizations I want to support through my estate.
But I’m increasingly drawn to the idea of giving some of it away while I’m here to watch.
After all, if someone I love will eventually receive something from me at 65, it seems worth asking:
Would some of it change their life more at 35?
*Prior to investing in a 529 Plan, investors should consider whether the investor's or designated beneficiary's home state offers any state tax or other state benefits such as financial aid, scholarship funds, and protection from creditors that are only available for investments in such state's qualified tuition program. Withdrawals used for qualified expenses are federally tax free. Tax treatment at the state level may vary. Please consult with your tax advisor before investing.
Tax and estate-planning laws change, and individual circumstances vary. Consult your tax, legal and financial advisors before making significant gifts or implementing an estate-planning strategy.
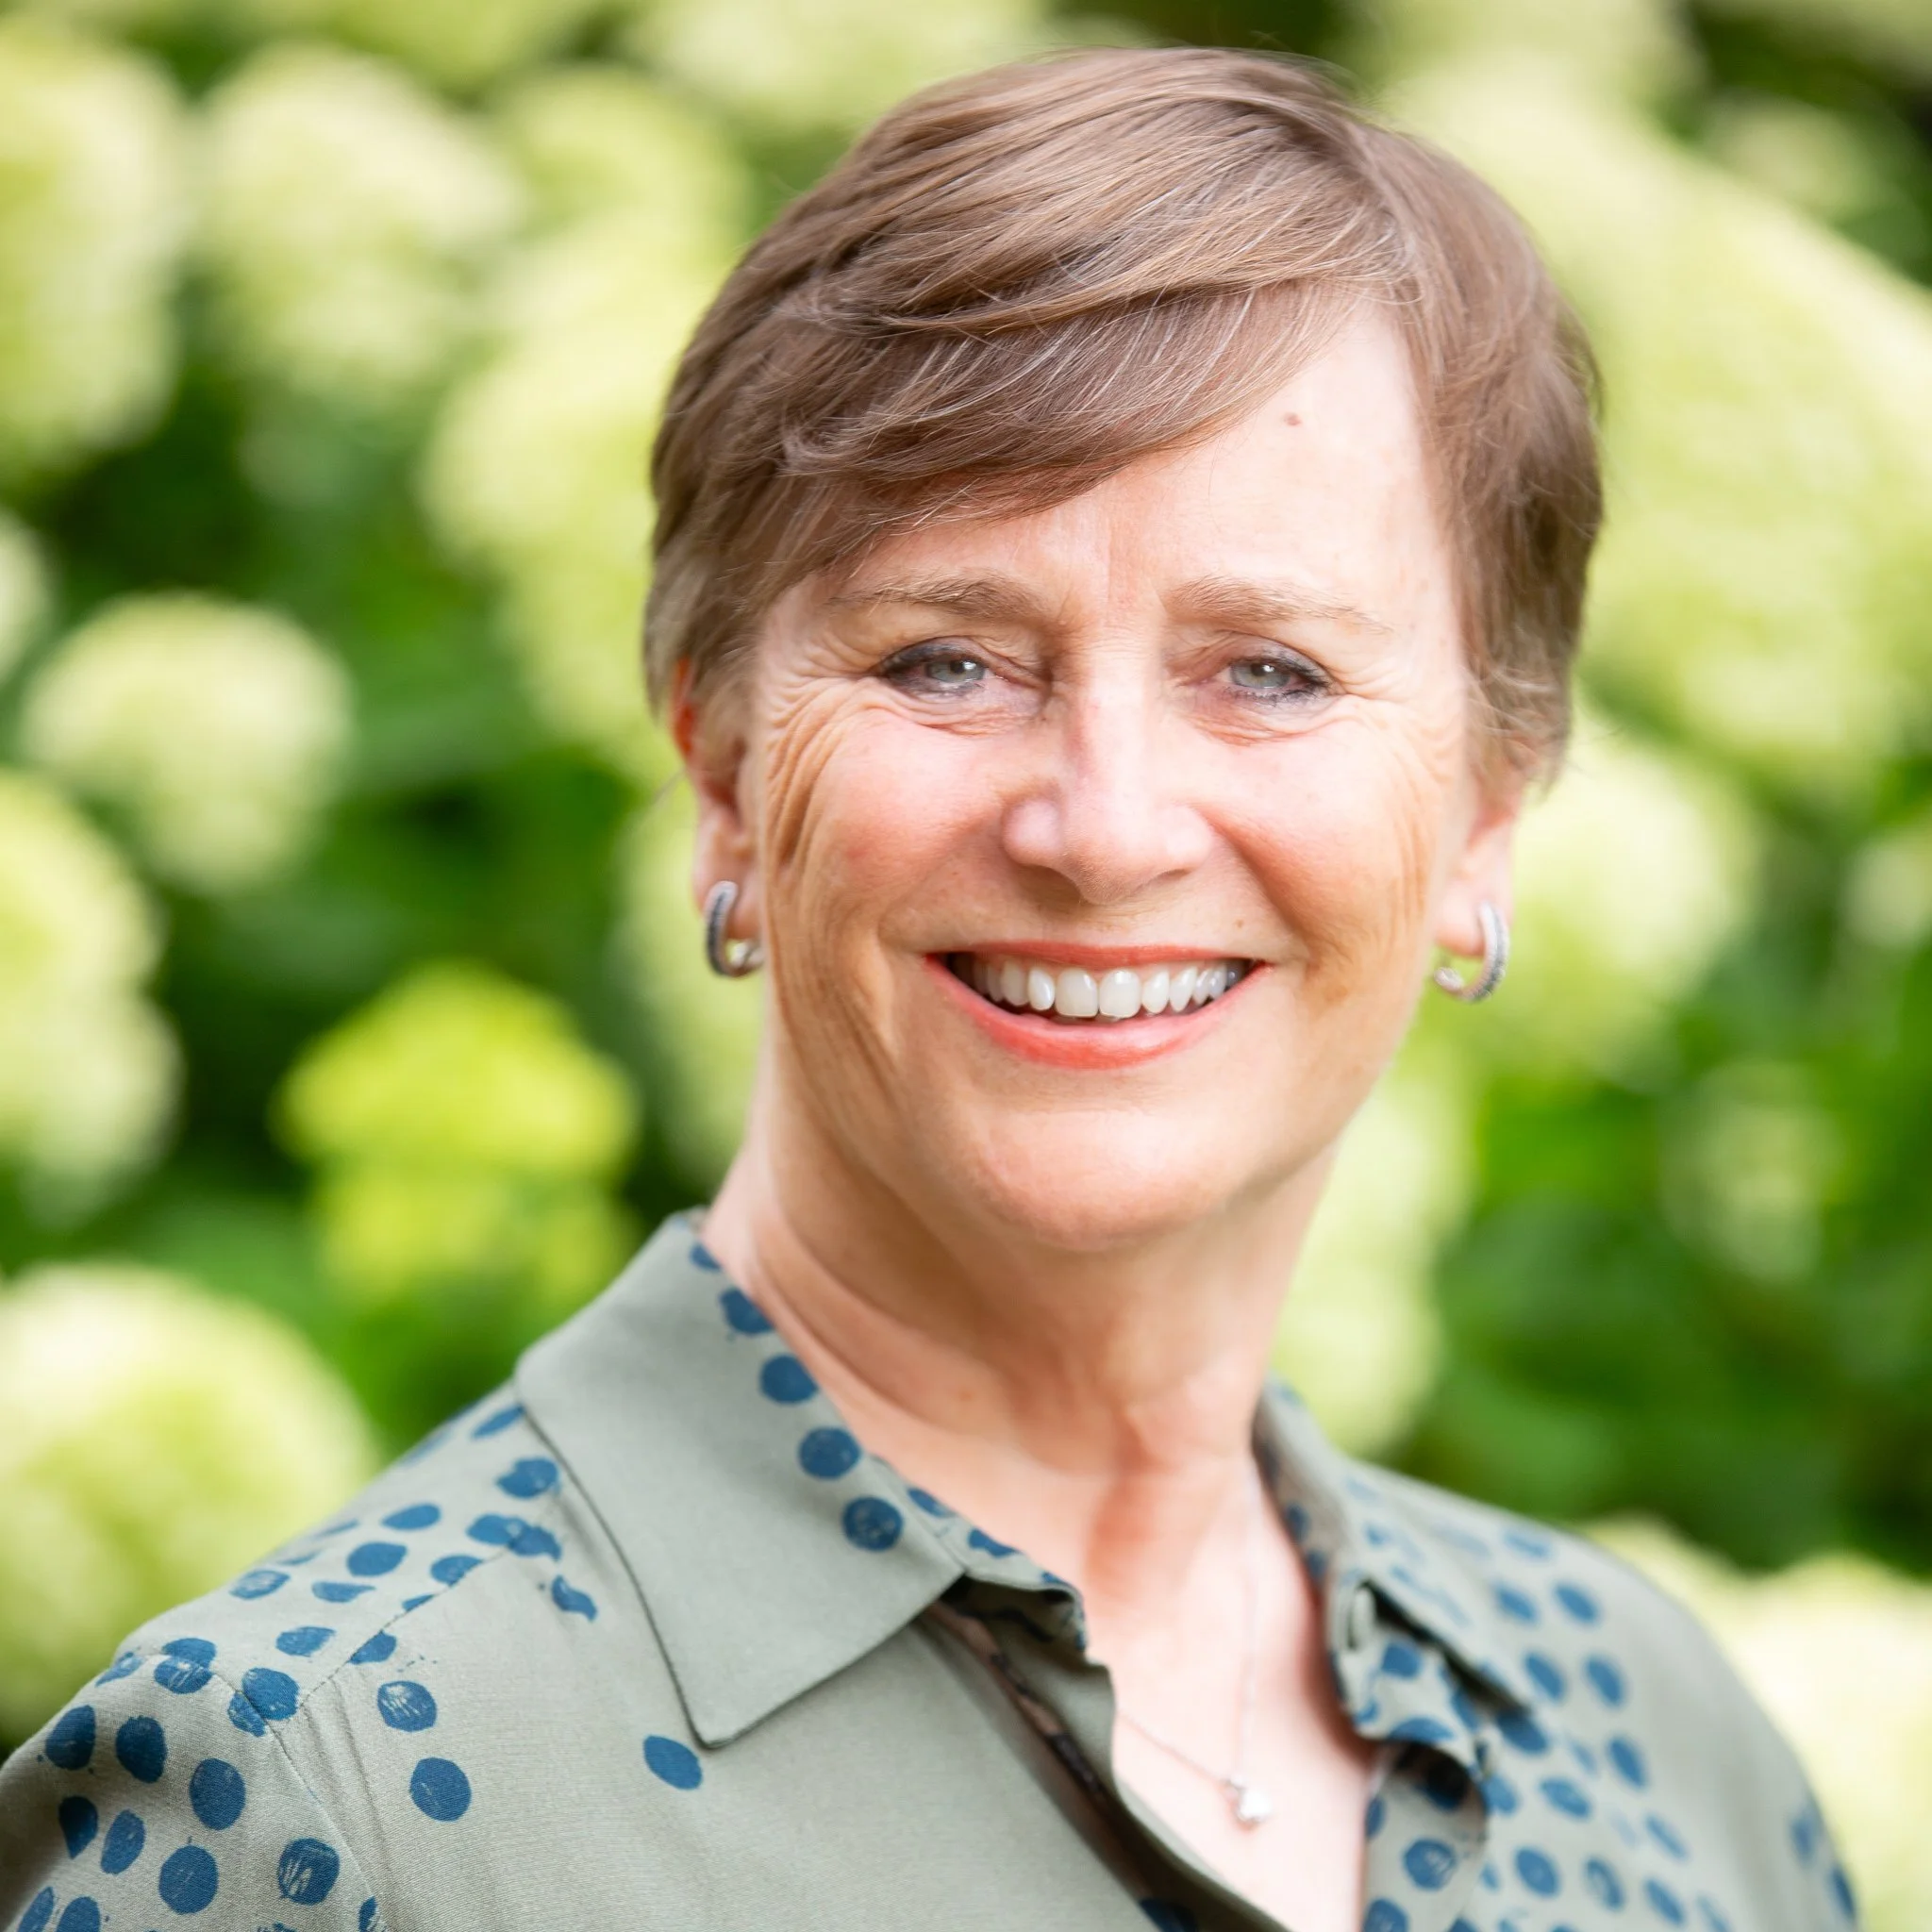
Nancy Knous, CEO, CFP®, CFS
Nancy began her career in the financial planning business in 1987. She is a proud Memphian who loves what she does and feels blessed to have done it for so long.
Benchmark Wealth Management
5855 Ridge Bend Road
Memphis, TN 38120
Securities and advisory services offered through LPL Financial, a Registered Investment Advisor, Member FINRA/SIPIC.
The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual.
There is no assurance that the views or strategies discussed are suitable for all investors or will yield positive outcomes.
Investing involves risk including possible loss of principal.
